Student Loan Stress Linked to Reduced Productivity, Higher Turnover, and Stalled Retirement
Want to know how student debt affects financial wellness? Get the facts and data in the 2026 Tuition.io Consumer Survey on student loan stress. Read...
4 min read
Tuition.io
:
Nov 19, 2026, 8:00:00 AM
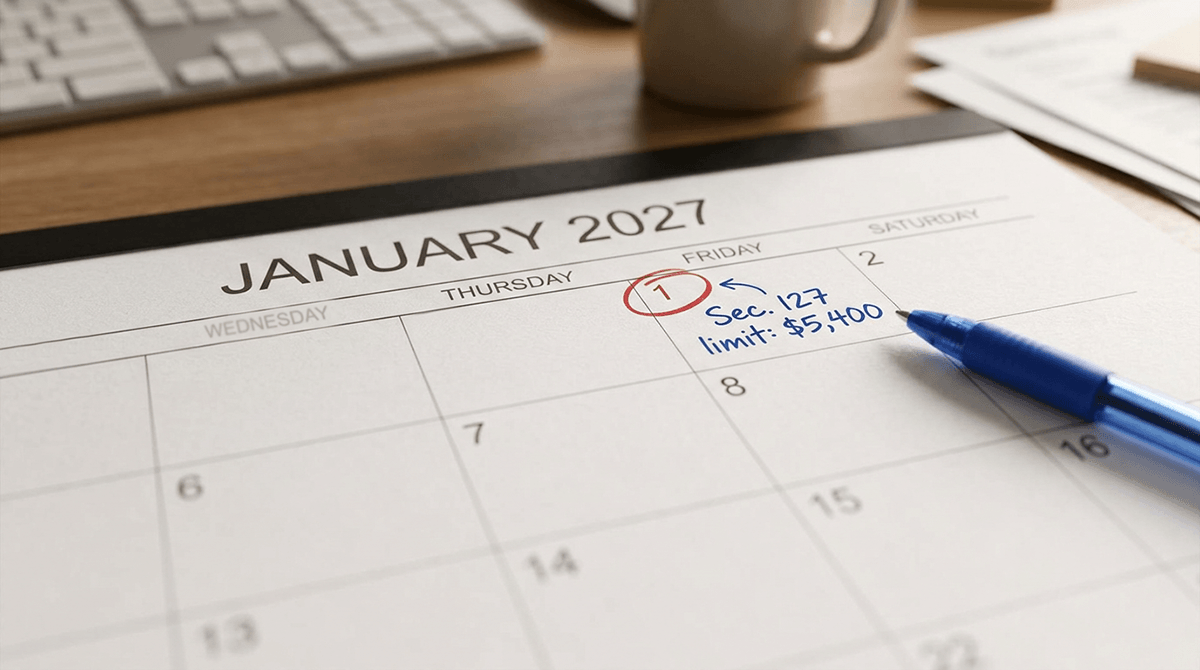
The IRS announced that the annual tax-free limit for Section 127 educational assistance will rise to $5,400 for 2027, up from $5,250. It is the first increase since the cap was set in 1986, and it applies to both Tuition Assistance and Student Loan Repayment Assistance benefits.
This briefing summarizes what changed, what it means for employer-sponsored education benefits, and the steps employers should take now.
New 2027 limit: $5,400 per employee, per calendar year (up $150, or 2.9%).
Effective date: Tax year 2027.
Official source: IRS Revenue Procedure 2026-35, released November 5, 2026.
Going forward: The limit will now adjust for inflation every year, in multiples of $50.
After nearly 40 years at $5,250, the Section 127 taxability cap now keeps pace with inflation.
The law behind it: The One Big Beautiful Bill Act (OBBBA), signed in July 2025, made Student Loan Repayment Assistance a permanent part of Section 127 and indexed the $5,250 cap for inflation starting with tax years after 2026.
One shared limit: The $5,400 cap is a combined annual total per employee. Tuition Assistance and Student Loan Repayment Assistance payments both count toward it.
Tax-free to both sides: Payments up to the limit are excluded from the employee’s federal taxable income and from payroll (FICA) taxes for the employee and the employer.
Above the limit: Payments over $5,400 are taxable wages, unless they qualify under another provision such as Section 132 ( job-related education).
Annual updates from here on: Expect a new limit to be announced each October/November alongside the IRS’s other inflation adjustments.
The new limit takes effect automatically under the Internal Revenue Code (IRC). Employer plans, systems, and vendors require an action.
PLAN DESIGN: A DECISION TO MAKE
Employers whose annual benefit is set at $5,250 today have two primary options:
Raise the plan limit to $5,400: Employees get the full tax-free value, and the benefit keeps pace with inflation. The added cost is up to $150 per participating employee per year.
Hold at $5,250: The budget stays flat and the benefit stays fully tax-free. The gap between the employer’s plan and the IRS limit will grow over time.
To size the increase, multiply the number of employees who use their full annual benefit by $150. For example, 200 employees at the maximum equals $30,000 in estimated additional spend.
Where a benefit is already set above $5,250, more of each payment is now tax-free. Employers should make sure payroll treatment reflects the higher threshold so employees aren’t over-taxed.
PLAN DOCUMENTS
Section 127 requires a separate written plan. Plans that reference the IRS tax limit of $5,250 as a fixed amount should be updated to reference the current annual IRS limit.
The IRS’s updated sample plan document (Publication 5993), released in April 2026 with revised Section 127 FAQs, is a useful starting reference. Employers should review any changes with their legal counsel.
PAYROLL, HRIS, AND VENDOR READINESS
Employers should confirm that whoever administers the benefit (an internal team, a payroll provider, or a third-party vendor) will apply the $5,400 limit effective January 1, 2027.
The cap is a combined total across all Section 127 benefits. If assistance is paid through more than one channel (multiple vendors, department budgets, direct reimbursement), confirm payments are tracked against a single annual cap per employee.
Confirm amounts above the cap are reported as taxable wages, and that ideally the cap will be updated each year without a manual workaround.
EMPLOYEE NOTICE
The IRS’s April 2026 FAQs clarify that employers must tell employees whether a Section 127 program exists and what its terms are. Employers should update benefit guides, enrollment materials, and intranet pages to show the 2027 plan limit.
Confirm the current plan limit. Check whether current Tuition Assistance and Student Loan Repayment Assistance benefits are set at $5,250, below it, or above it.
Decide whether to raise or hold. Weigh the added cost of up to $150 per participant against retention, recruiting, and upskilling goals. Make the call before January 1, 2027.
Update your plan document. Replace any hard-coded $5,250 with a reference to the new annual IRS limit, using the IRS sample plan as a guide.
Confirm with your administrator. Ask the payroll provider or benefits vendor how and when they will apply the $5,400 limit, and whether future adjustments will be automatic.
Check payroll and HRIS. Make sure all Section 127 payments, across every channel, count toward one annual cap and that excess amounts are taxed correctly.
Tell employees what’s changing. Employers must inform employees of the program and its terms. Update materials with the 2027 plan limit, whether it rises or holds steady.
Tuition.io administers Section 127 Tuition Assistance and Student Loan Repayment Assistance benefits for employers nationwide. For our clients, the 2027 limit will adjust automatically on January 1, with no action required. Other support includes:
Built-in tax compliance: IRS annual limits are applied automatically. When Tuition.io administers both benefits, each employee’s Tuition Assistance and Student Loan Repayment Assistance spending is tracked under one combined limit.
Budget impact modeling: Estimates of what raising a plan limit would cost, based on the employer’s workforce.
Plan design advisory and employee communications: Guidance on benefit structure and best practices, plus support announcing changes to employees.
Schedule a time for guidance on the plan designs of your education assistance benefits, including Tuition Assistance, Student Loan Repayment, SECURE 2.0 Retirement Match and PSLF services.
Tuition.io is the leading employer-sponsored financial wellness platform specializing in student loan benefits and tuition assistance administration. We help employers hire, retain, and upskill talent by addressing the dual challenges of historic student debt and the ROI of higher education.
Our Industry Briefings are intended to help employers, benefit brokers and advisors, record keepers, and other workforce professionals be informed about trends in the dynamic areas of student loan debt, higher education, and their impact on the U.S. workforce. Visit Tuition.io and subscribe.
This briefing is for general information and is not tax or legal advice.
Want to know how student debt affects financial wellness? Get the facts and data in the 2026 Tuition.io Consumer Survey on student loan stress. Read...
Explore Tuition.io's 2026 survey of 525 frontline workers: why 78% demand upfront tuition, transparent promotion paths, and direct-pay career...
How does the IRS Private Letter Ruling impact student loan retirement matching and tax-free benefits? Get the compliance answers in our industry...